Wealthfront vs Betterment 2026: Which Robo-Advisor Wins for Your Money?
Wealthfront and Betterment are the two robo-advisors most people end up comparing, and for good reason: they both charge a 0.25% management fee, both build low-cost ETF portfolios, and both bolt a high-yield cash account onto the side. On paper they look like twins. In practice, the differences in cash APY, account minimums, tax features, and how you actually get charged can push you toward one or the other depending on how much you have and how you like to manage it.
This Wealthfront vs Betterment 2026 breakdown covers current fees, cash APYs, minimums, and the specific situations where each one wins. Every fee, rate and minimum below was re-checked on Wealthfront’s and Betterment’s own pages on October 11, 2026. Cash rates are variable, so the date each one was quoted is shown next to it.
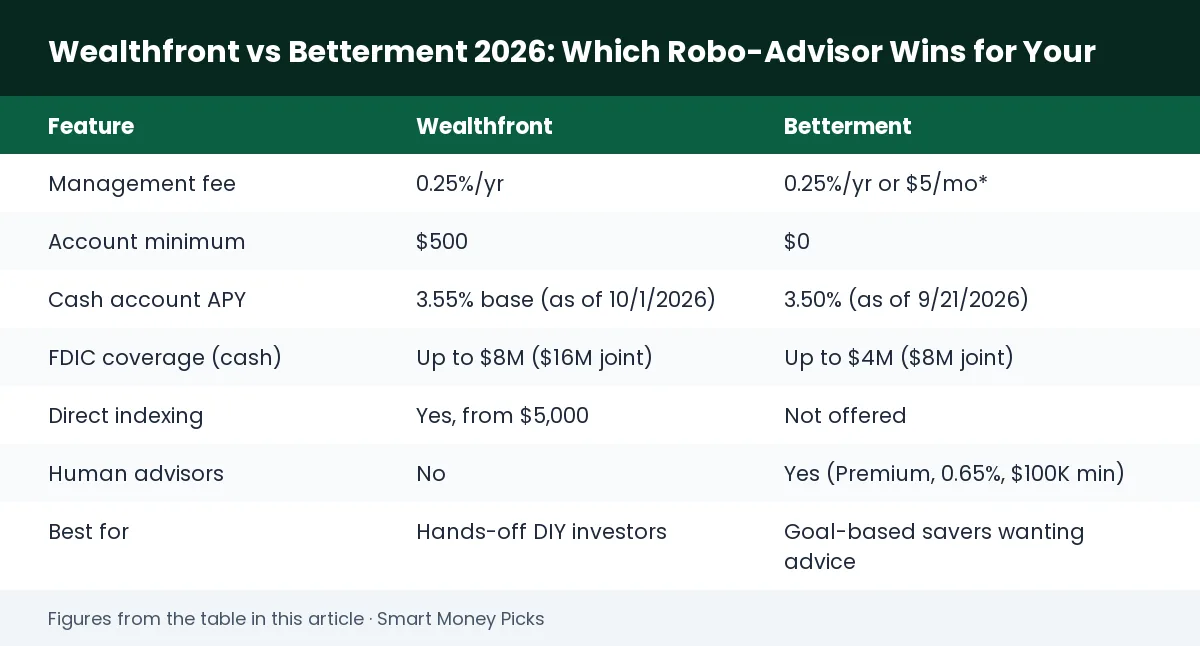
Quick Comparison
| Feature | Wealthfront | Betterment |
|---|---|---|
| Management fee | 0.25%/yr | 0.25%/yr or $5/mo* |
| Account minimum | $500 | $0 |
| Cash account APY | 3.55% base (as of 10/1/2026) | 3.50% (as of 9/21/2026) |
| FDIC coverage (cash) | Up to $8M ($16M joint) | Up to $4M ($8M joint) |
| Direct indexing | Yes, from $5,000 | Not offered |
| Human advisors | No | Yes (Premium, 0.65%, $100K min) |
| Best for | Hands-off DIY investors | Goal-based savers wanting advice |
*Betterment charges $5/month on its standard investing plan if your household balance is under $24,000 and you don’t have at least $200/month in recurring deposits. Above that threshold, it’s 0.25% per year.
Fees — Close, But the Details Matter
Both charge the same headline rate: 0.25% per year on your invested balance. On a $50,000 portfolio, that’s about $125 a year either way. This is where the “they’re basically the same” reputation comes from, and for a mid-size account it’s fair.
Wealthfront’s approach
Wealthfront keeps it simple: a flat 0.25% annual advisory fee on its Automated Investing Account. Wealthfront’s own pricing page puts a $15,000 account at about $3.18 a month. There is no flat-fee tier for small balances, but you need $500 to open an automated account.
Betterment’s approach
Betterment’s standard investing plan is also 0.25% per year, but with a catch on small balances. If your household balance is under $24,000 and you don’t have at least $200/month in recurring deposits set up, you’ll be charged a flat $5/month instead. On a $2,000 balance, $5/month works out to an effective 3.0% annual rate, which is steep. Once you cross $24,000 or turn on automatic deposits, you flip to the standard 0.25% and the math looks much friendlier.
Betterment also offers a Premium plan at 0.65% per year, which adds access to Betterment’s financial experts. It requires an eligible investment balance of at least $100,000. Above $1 million, Betterment says eligible balances get progressive fee discounts. Wealthfront has no human-advice tier at all; its whole pitch is software instead of people.
Fee edge: Betterment
- $0 minimum lets you start with any amount
- Same 0.25% once you’re above $24K or auto-depositing
- Optional human advice on Premium ($100K+)
Fee edge: Wealthfront
- No flat-fee trap on small balances
- Predictable 0.25% from dollar one (above the $500 min)
- Direct indexing available from $5,000
Cash Accounts — Near-Tied Base Rates, Different Promos
Both companies want to be where your emergency fund lives, and both offer FDIC-insured cash accounts through partner banks.
Betterment Cash Reserve pays 3.50% APY (variable, as of 9/21/2026) with no account fees and no minimum balance, though Betterment notes a $10 minimum deposit to earn the base rate. New clients who make a qualifying deposit get a 0.75% boost, for 4.25% APY on up to $1 million through February 15, 2027. FDIC coverage through Betterment’s program banks goes up to $4 million for an individual and $8 million for a joint account. Cash Reserve itself is a savings account; for a debit card and everyday spending, Betterment offers a separate Betterment Checking account issued by nbkc bank.
Wealthfront’s Cash Account pays a 3.55% base APY (as of 10/1/2026). Two boosts sit on top: an ongoing +0.25% for clients who fund an investing account and keep up monthly deposits (a $1,000 monthly direct deposit, or $2,500 in recurring deposits), and a +0.65% boost for new clients that lasts three months on up to $150,000. Stacked, that is the “up to 4.45% APY” on Wealthfront’s page. The Cash Account also works like checking, with a debit card, bill pay and reimbursement of two out-of-network ATM fees a month, and it spreads deposits across program banks for up to $8 million in FDIC coverage ($16 million joint).
On base rates the two are close: 3.55% at Wealthfront against 3.50% at Betterment. The promos are where they split. Wealthfront’s headline 4.45% includes a boost that ends after three months, while Betterment’s 4.25% new-client rate runs until February 2027. If you are parking a large balance for the next several months, Betterment’s offer pays for longer; if you want one account that replaces checking, Wealthfront is the stronger cash hub. Both rates are variable, so check the live numbers before you move money.
Portfolios and Tax Features — Wealthfront’s Direct Indexing
Both build diversified portfolios of low-cost index ETFs across US stocks, international stocks, bonds, and real estate, and both do automatic rebalancing and tax-loss harvesting on taxable accounts. For most investors under six figures, the portfolios themselves are close enough that it won’t be the deciding factor.
The separator is direct indexing. Instead of holding a single index ETF, Wealthfront’s direct indexing portfolios (such as its S&P 500 Direct) buy the individual stocks in the index, which creates many more chances to harvest tax losses on single positions. Wealthfront’s own comparison table lists a $5,000 minimum and an annual advisory fee of 0.09% to 0.12% for these accounts (accurate as of September 10, 2026, per Wealthfront). For a taxable account, that can add up to meaningful after-tax savings. We did not find a direct indexing option on Betterment’s consumer pricing page; its tax-loss harvesting works at the ETF level.
Betterment counters with better goal-based tools. You can set up separate buckets for a house down payment, a wedding, or retirement, each with its own target date and risk glide path, and get specific advice on whether you’re on track. Wealthfront has goals and a strong financial-planning tool (Path), but Betterment’s multi-goal structure and optional human advisors make it feel more hand-held.
Who Should Use Each
Choose Wealthfront if you’re a hands-off investor who wants set-it-and-forget-it software, you want direct indexing in a taxable account (from $5,000), or you want a cash account that can double as your primary checking with up to $8 million in FDIC coverage. You’ll need $500 to start an automated investing account.
Choose Betterment if you’re starting small (its $0 minimum and $5/month or 0.25% structure is friendlier once you automate deposits), you want a cash promo that runs for months rather than weeks, or you expect to reach $100,000 and want access to Betterment’s financial experts through the Premium plan. It’s also the more natural fit if you like organizing money around specific goals. For a closer look at its fees, Cash Reserve, and Premium tier, read our full Betterment review.
What About Ellevest?
If you were weighing Ellevest as a third option, that choice no longer exists. Ellevest’s own site says it stopped offering automated investing on April 10, 2025, and that qualifying accounts moved to Betterment in kind, with positions (other than mutual funds) transferred as they were. Ellevest now focuses on wealth management and financial planning. So for an automated, low-cost portfolio today, the comparison really is Wealthfront vs Betterment.
Getting Started with Either
Both take about 10 minutes to open. You answer a short risk questionnaire, link a bank account, and fund it — $500 for Wealthfront, any amount for Betterment. From there the software handles allocation, rebalancing, and tax-loss harvesting automatically. If you want to understand what these platforms are doing under the hood before you commit, a plain-English primer on index investing is worth an afternoon.
Two books that explain the low-cost, passive strategy both robo-advisors are built on: The Little Book of Common Sense Investing by John Bogle, and A Random Walk Down Wall Street by Burton Malkiel. Both make the case for exactly what Wealthfront and Betterment automate for you.
Related reading: How to Start Investing With $500 in 2026: A Beginner's Step-by-Step Plan
FAQ
Is Wealthfront or Betterment cheaper?
Both charge 0.25% per year, so at most balances they cost the same. Betterment is cheaper for small accounts because it has no minimum, but watch its $5/month flat fee if your household balance is under $24,000 and you’re not auto-depositing $200/month. Wealthfront requires $500 to start but never charges a flat fee.
Which has the higher cash account APY?
On base rates Wealthfront is slightly ahead: 3.55% APY (as of 10/1/2026) against 3.50% for Betterment Cash Reserve (as of 9/21/2026). With new-client promos, Wealthfront reaches up to 4.45% but part of that lasts only three months, while Betterment’s 4.25% offer runs through February 15, 2027. Rates are variable, so check both sites before you decide.
Can I move my portfolio from one to the other?
Yes. Brokerage accounts can usually move between firms by ACATS transfer, and an in-kind transfer avoids selling. Check each firm’s current fee schedule for any outgoing-transfer fee first, and remember that selling positions in a taxable account can trigger capital gains.
Do either offer human financial advisors?
Only Betterment, through its Premium plan at 0.65% per year with a $100,000 minimum eligible balance, which adds access to its financial experts. Wealthfront is software-only.
What happened to Ellevest’s robo-advisor?
Ellevest stopped offering automated investing on April 10, 2025. Qualifying accounts transferred to Betterment unless the client opted out, per Ellevest’s own site.
For more on automated investing, see our homepage and our roundup of the best finance apps. You can also see how both stack up against the field in our ranking of the best robo-advisors.
Disclosure: We have no affiliate relationship with Wealthfront, Betterment or Ellevest and earn nothing if you open an account through the links on this page. This is not financial advice — it’s for informational purposes only. Investing involves risk, including possible loss of principal. Consider your own situation or consult a licensed advisor before investing.